Insurance
National Risk and Market Context
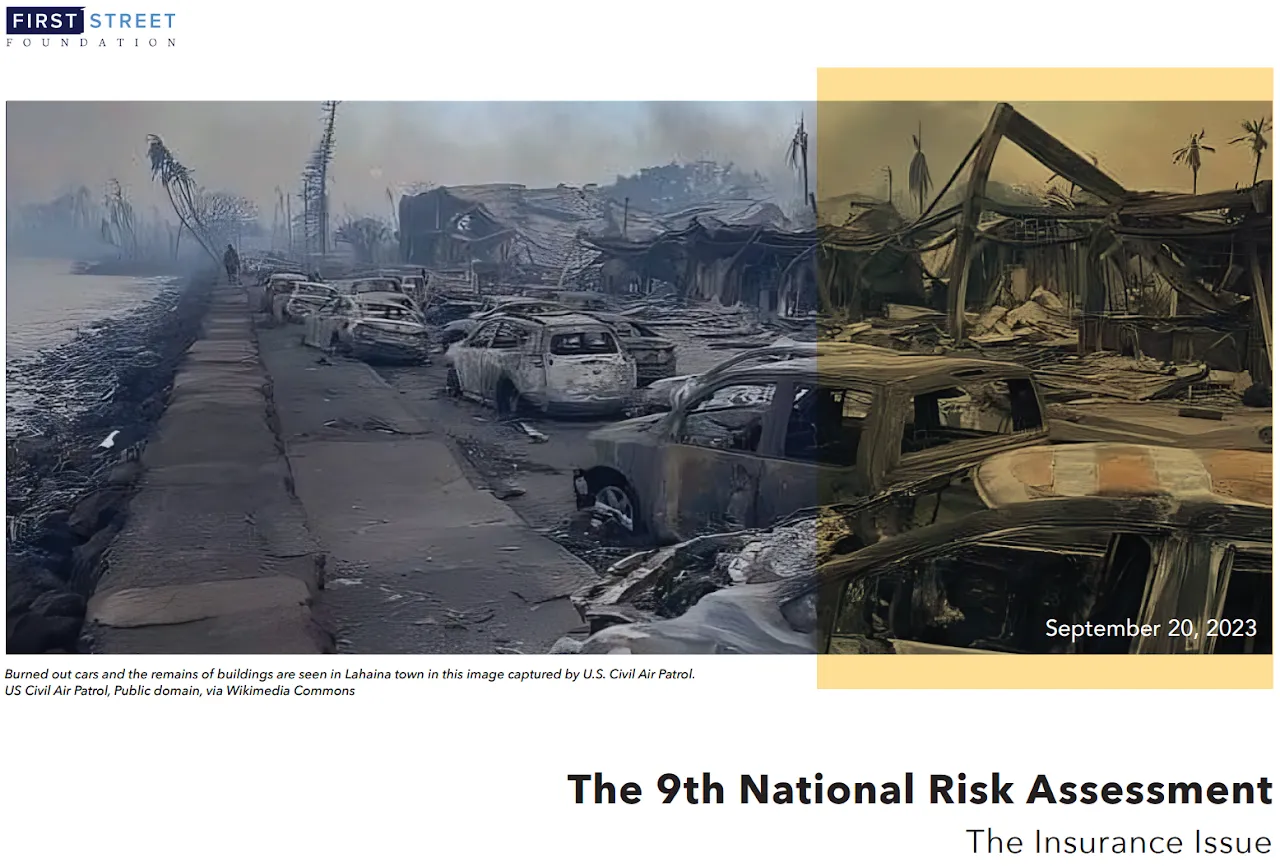
After years of steep increases, the property insurance market leveled off in 2025 and 2026.
Commercial property premiums fell 6.3% in the second quarter of 2026, and three in four survey respondents reported increased property insurance capacity (CIAB survey, 08/20/26). In Washington, homeowners rate increases slowed from 21.7% in 2024 to 8.9% in 2025, and rates were flat in early 2026 (Washington Insurance Commissioner data, 05/21/26). Wildfire risk is the exception: insured losses from 2026 Washington wildfires are projected at more than $600 million (Insurance Journal, 09/08/26).
Property Insurance Prices, 2006 to 2025
View Data
| Year | Homeowners | Commercial package |
|---|---|---|
| 2006 | 100 | 100 |
| 2007 | 102 | 100 |
| 2008 | 104 | 99 |
| 2009 | 106 | 100 |
| 2010 | 109 | 101 |
| 2011 | 113 | 102 |
| 2012 | 116 | 102 |
| 2013 | 120 | 104 |
| 2014 | 123 | 105 |
| 2015 | 127 | 107 |
| 2016 | 130 | 108 |
| 2017 | 131 | 108 |
| 2018 | 133 | 109 |
| 2019 | 136 | 112 |
| 2020 | 139 | 117 |
| 2021 | 140 | 121 |
| 2022 | 142 | 127 |
| 2023 | 150 | 138 |
| 2024 | 167 | 152 |
| 2025 | 181 | 170 |
Condo Facts
No agency publishes master-policy premiums, so these are surveys, a legislative finding and unit-owner policy data.
91% to 93%
Associations Reporting Higher Premiums at Renewal
Share reporting an increase, April 2023 (n=895) vs April 2025 (n=509). Measures how many, not how much.
11% to 23%
Associations Non-Renewed or Canceled
Survey of association managers and boards; not a random sample.
300% to 600%
Hawaii Condo Master Premium Increases, 2024
Finding stated by the Hawaii Legislature, not measured data.
+57.9% vs +33.8%
Colorado vs US Homeowners Premium Rates, 2018-2023
Homeowners rates, not condo master policies.
| Location | Average Premium |
|---|---|
| US | $658 |
| FL | $1,146 |
| TX | $999 |
| LA | $992 |
| CO | $657 |
| WA | $512 |
| OR | $483 |
Unit-owner policy, one year only. NAIC Homeowners Report, 2023, Table 5
Four Primary Drivers of Property Insurance Premiums
Colorado HOA Homeowner Toolkit- (Catastrophic) Losses
Attributed to Climate Change - Construction costs
- Excessive litigation
- Reinsurance rates
Risk Tools
![NOAA Sea Level Rise Viewer]](/assets/images/resource/Insurance/NOAASeaLevelRiseViewerRiskFactor.com.webp)
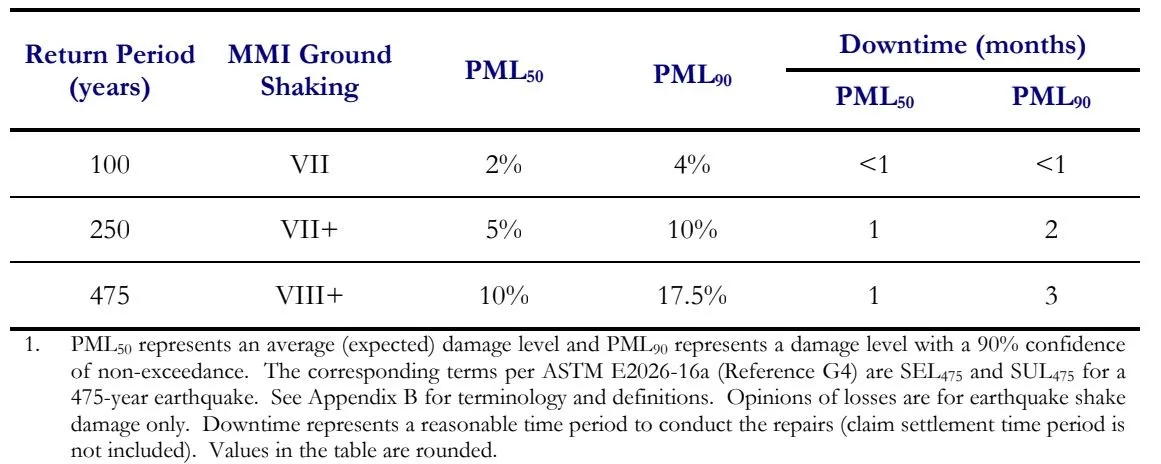
Example Seismic Probable Loss StudyLearn More
Example Seismic Probable Loss Study
Association and Unit-Owner Coverage
Types of Insurance Explained · Your association's insurance varies based on your declaration of covenants, conditions and restrictions (CC&Rs) and your state statutes. Washington and many other states require specific scope for property insurance that serves as primary in the event of a loss and for other types of insurance such as director and officer's (D&O) coverage. Notably, regardless of your state, individual units / homes are often responsible for paying in-unit claim deductibles.
Association Coverage
Read the policy scope, governing-document requirements and deductible examples.
Unit-Owner Coverage
Compare the coverage categories in the page’s HO-6 breakdown.
Washington Guidance
Find state references, volunteer coverage and dated rate examples.
An association's violation of its own governing documents to procure specific insurance coverage does not bind an insurance company to cover losses outside of the policy actually purchased / in force.
Five Things to Check Before a Loss
- You may owe the master policy deductible. Many declarations make the unit where a loss starts pay up to the association's deductible.
- The headline limit is not what pays. Sub-limits and separate deductibles cap water, mold, equipment and more.
- Loss adjustment expense coverage often excludes consultants, third-party project management, and public adjusters.
- Your HO-6 should cover deductibles and loss assessments. Match its limits to your association's deductibles.
- Vendors need their own insurance. Require a certificate of insurance naming the association as additional insured.
Your Guide to HO-6 Insurance
As a condo owner, your property is protected by two distinct insurance policies that work together:
1. Your Association's Master Policy
Paid for by owner assessments, the master policy covers the infrastructure and common elements (roof, hallways, etc.). Washington law requires that the association's master policy is primary, but allows associations to assess owners up to the policy deductible which can vary between $5,000 to $250,000. Associations are legally responsible to ensure that both the common elements and units are restored following a loss.
Property Coverage
Damage to shared parts of the building, such as the roof and hallways.
In the Washington example, property coverage includes common and limited common elements and units, including their fixtures, improvements and appliances. It does not cover owners' personal belongings. Check your own policy and declaration for the scope.
The example includes earthquake sprinkler leakage and loss of rents, with varying sub-limits.
- Ratable Limit
- Valuation GRC, RC, ACV
- Co-Insurance Penalty Agreed Amount, 90%, 80%
- Personal Property
- Loss of Maintenance Dues
- Deductible
- Water Loss Deductible
- Sewer and Drain Backup
- Mechanical Breakdown
- Difference in Conditions Earthquake and flood limits and deductibles
Sub-Limits, Deductibles and Exclusions
A master policy's headline limit is rarely what pays for the loss you actually have. That same Allianz policy insures the buildings for about $123 million, but:
| Item | Example policy terms |
|---|---|
| Earthquake | Capped at $5,000,000 per event and per year, with a 3% of value deductible (minimum $25,000 per building). |
| Flood | Capped at $25,000,000 per event and per year. |
| Water damage and sewer or drain back-up | A $50,000 deductible, plus a 72-hour wait before lost income is covered. |
| Mold remediation | Capped at $100,000 and must be reported within 30 days; general liability excludes mold entirely. |
| Communicable disease | $25,000 per year. |
| Excluded | Wear and tear, rot, corrosion, latent defects, and faulty workmanship and maintenance. Damage those conditions cause, such as water from a corroded pipe, may still be covered, so file the claim and let the adjuster decide. |
| Vacancy | Coverage can be limited or cancelled for buildings left vacant for long periods; the policy sets the conditions. |
View your policy coverage documents for the full schedule of sub-limits, and compare it with your declaration's insurance requirements.
General Liability
Injuries and accidents in shared areas, or caused by them.
General Liability insurance covers certain types of bodily injury and other liabilities. Many General Liability policies include $5,000 of no-fault liability coverage where the insurance carrier pays up to $5,000 without the need for litigation.
Washington example: In the Washington example, unit owners are additional insureds for common-area activities, but not for activities inside their units. Liability coverage can have separate limits per occurrence and per year.
Your Vendors Need Their Own Insurance
Associations often do not know what their own insurance covers, and they rarely demand that the professionals they hire, especially management companies, carry enough coverage.
- Hired & Non-Owned Auto can cover employees, board members and others conducting association business.
- General liability: Your property manager may qualify as an insured under your general liability coverage for bodily injury or property damage caused while working for you. That does not extend professional liability coverage to them.
- Additional insured and waiver of subrogation: Your vendor contracts should require the vendor to name the association as an additional insured on its general liability policy and to waive subrogation against the association. Be cautious about agreeing to waive your own insurer's right to recover from a vendor; that can cost the association money after a loss. Read the contract and policy together.
Require a certificate of insurance (COI) from every vendor showing general liability with the association as additional insured, plus professional liability and cyber coverage where the work calls for it, and check it every year.
Consider a Contract Addendum that puts these liability requirements in writing for every vendor doing on-site maintenance, repair or replacement work.
Directors & Officers (D&O)
Claims over decisions by board members, officers and managers.
Coverage for claims against the board is subject to policy limitations.
D&O typically covers board and committee members, but not all volunteers.
Good reads: What Is Not Covered by a D&O Insurance Policy? · Does my Association Really Need D&O Liability Insurance?
Crime/Fidelity
Theft of the association’s money.
Employee dishonesty can cover theft of association funds by board members, trustees or the property management firm.
- Computer Fraud and Funds Transfer Fraud
- Deductible
Ordinance or Law
The extra cost of rebuilding to meet newer building codes.
- Ordinance or Law Coverage A: Undamaged Portion of the Building
- Ordinance or Law Coverage B: Demolition
- Ordinance or Law Coverage C: Increased Cost of Construction
Umbrella
More liability protection once other policy limits run out.
- Professional liability: A typical association umbrella excludes any loss "arising out of the rendering or failing to render professional service or advice." Do not count on the association's umbrella or general liability to cover a professional's mistakes. If a manager, engineer or consultant makes an error that costs the association money, you look to their professional liability policy.
Cyber Liability
Data breaches and other online security problems.
- Cyber: Your association's policy cannot cover your management company; it is a separate entity. If it handles owner data or association funds, require it to carry its own cyber coverage and prove it.
Association Coverage, Deductibles and Case Law
What Insurance Coverage Does My Association Carry?
Damage / Loss Flow ChartFollow the path from a loss to payment.
This flow chart is one example applicable to condominium communities. Your governing documents may have different requirements.
- Loss Attributable to One or More Units?YESResponsible Unit Owner(s) pay to restore losses within the Association’s insurance deductible.
Does not include miscellaneous backups, water pipe bursts, etc.NO ↓ - Common Elements Affected?YES> Association pays to restore Common Elements (including some LCEs).
> IF losses include one or more Units, costs within the Association’s insurance deductible are assessed proportionately to losses between each affected Unit and the Common Elements.NO ↓ - Multiple Units Affected?YESAffected Unit Owners pay to restore losses in proportion to loss per Unit within the Association’s insurance deductible.NO ↓
- One Unit AffectedYESAffected Unit Owner pays to restore losses within the Association’s insurance deductible.
- Exhibit C
- Exhibit E
- 4.2 - 4.3: Unit Boundaries + Items Included in Units
- 5.1: Common Elements
- 10.2.8: Entry for Repairs
- 11.11.2: Fixtures
- 13.7.3 - 13.7.7: Insurance Related
- 20.1: Utility Failure
- Dwelling / Building Property
- Water Backup
- Earth Movement
Association common funds -OR- master insurance policy pays to restore losses in excess of deductible up to policy limits.
“TOTAL” LOSS > Costs that exceed insured limits = Common Expense; potentially “walk away”
Multi-family Property Insurance RemindersDeductibles and restoration.
Multi-family Property Insurance Reminders
1) unit owners/homeowners are almost always responsible for in-unit/home losses up to the association's primary insurance deductible
IF something in Unit X causes a loss, Unit X is probably responsible for costs up to the association's primary insurance deductible
2) except for #1, responsible parties for losses within a deductible limit are generally in proportion to the areas damaged
3) governing documents typically require owners to carry insurance that covers any potential deductibles and loss assessments for ANY insurance coverage held by the Association including optional coverage such as earthquake and earth movement
4) While a Board often has discretion to file claim, the responsibility to restore a loss is governed by statute and your declaration.
- Unit owners / homeowners are generally NOT required to wait for their association to "manage" losses within their unit.
Questions to Ask Your BoardOwner and master policy checks.
Does your association monitor and enforce owners' insurance requirements? This is a commonly overlooked risk.
Does your Declaration + Master Policy: include or exclude equipment, improvements, and betterments within units?
Does Your Insurance Match Your Declaration?Coverage requirements and cases.
Does Your Association’s Insurance Match the Requirements of Your Declaration / CC&Rs?
- Metropolitan Property and Casualty Insurance Company v. West Bend Mutual Insurance Company (2023) — Indiana Court of Appeal
Farmers' App. Vol. II p. 116 (emphasis added). Though it appears that the condominium association may have failed to fulfill its obligations under the Declaration, we conclude that it is of no moment. The trial court did not err in granting summary judgment to West Bend.
- Pike & Va. No. 8, LLC v. Pike & Virginia Condo. Association — Washington Court of Appeal
Water Loss and PreventionSurvey and plumbing guidance.
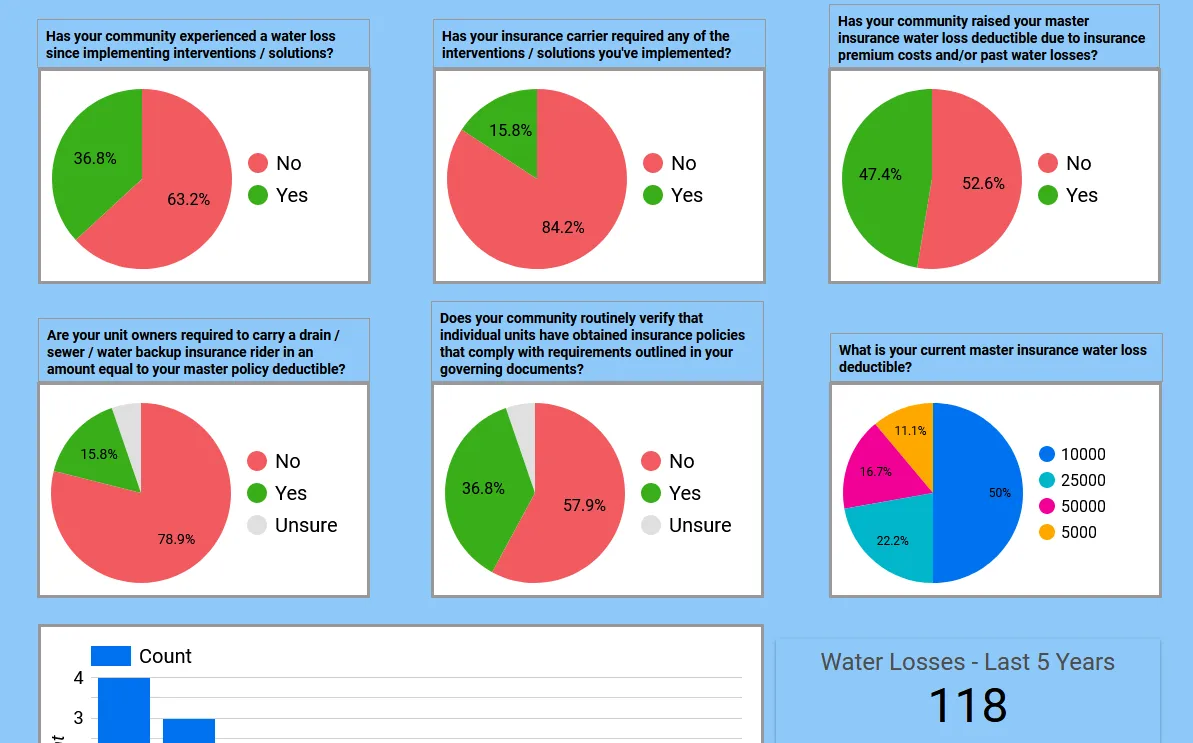 Multi-family residential property water loss & prevention Plumbing
Learn more about preventing water losses on our Plumbing Page
Learn more about preventing water losses on our Plumbing Page
Risk Management ResourcesRisk and insurance guidance.
Loss Adjustment Expense and Project Management
Many master policies include loss adjustment expense coverage (often capped at $100,000 per loss) that pays the extra cost of documenting a covered loss: extra staff wages to prepare inventories, accountant fees, appraisals and gathering loss data for your proof of loss.
But loss adjustment expense coverage often excludes fees for legal counsel, public adjusters, insurance agents or brokers, property managers or consultants, and the cost of proving a loss is covered.
Many management companies sell off-site "project management" after a loss. It is expensive, often ineffective, and rarely reimbursed. Insurers generally pay for that coordination when it is part of the mitigation and restoration contractors' work; they are on site and can work directly with owners.
Associations have learned this the hard way. One Washington condominium spent $50,000 to $100,000 from its operating fund over a few years on management company project management that was largely wasteful.
Before signing a project management agreement: read your policy's Loss Adjustment Expense section, ask the adjuster in writing whether the fee is reimbursable, and have the restoration contractor's scope include coordination.
Negligence and Deductible Responsibility
Understand the difference between gross negligence / willful misconduct and ordinary negligence.
Some state statutes extend owner’s liability beyond insurance deductible limits.
2. Your HO-6 Unit Policy
HO-6 is your individual unit policy that's designed to cover what the master policy does not, including your dwelling (Coverage A) up to the master policy deductible, your personal belongings, and personal liability.
HO-6 Coverage Types
How Insurer Terminology Can Differ
Safeco HO-6 Policies
Terminology and coverage differ between insurers. For example, Safeco HO-6 policies cover you differently depending on when your initial policy was issued.
Policies Issued Before 01/18/25
- Dwelling coverage is automatically set at 10% of Coverage C (Personal Property).
- The Optimum Package Endorsement increases Dwelling coverage to 100% of Coverage C.
- These "legacy" policies do not have Coverage L and use prior naming conventions.
New Policies Issued After 01/18/25
(Does not apply to renewals of older policies)
- Policies should include Coverage L for "Condo Building Items."
- Even if Coverage L is absent, a base of 10% of Coverage C still applies for Dwelling coverage by default.
Your interior, belongings, living expenses and liability: compare the protection and common gaps.
Want to know more? View Master Policy coverage and What is an HO-6 Condo Insurance Policy? A Complete Guide
Who pays? See deductible responsibility reminders
Dwelling (A)
Your interior walls and permanent improvements.
Covers your unit's interior structures. The amount you need depends on your association's master policy.
Example: A damaged interior wall.
Washington law (RCW 64.90.470) requires the master policy to cover units, including improvements, unless the declaration states otherwise. For this reason, your dwelling coverage need not exceed the master policy deductible plus the cost of betterments and improvements (if excluded from policy coverage by your declaration).
RCW 64.90 (WUCIOA) will apply to all associations in WA as of 01/01/28.
- What it covers
- Covers permanent improvements within the unit boundaries generally delineated by outside wall studs, the sub-floor and the ceiling
- Common gap / deductible
- Review declaration and master policy
Personal Property (C)
Your belongings and the cost to replace them.
Covers belongings not attached to the unit (furniture, electronics, etc.). Aim for Replacement Cost coverage, which pays to buy new items, not their depreciated value. Standard coverage for certain items can be limited; see the Riders section for more.
Example: Furniture damaged in a fire.
- What it covers
- Covers items that are not permanently attached to your Unit ceiling, floor and/or walls
- Common gap / deductible
- Certain types of personal property (e.g. fine art, jewelry, etc.) require a rider
Loss of Use (D)
Living expenses when a covered loss displaces you.
Helps pay for additional living expenses if a covered event makes your condo uninhabitable.
Example: A hotel stay after a covered loss.
Important: Major repairs can take many months, or even years. Ensure your policy can cover long-term displacement.
- What it covers
- Covers expenses such as hotel rooms and moving costs during a period of time when your Unit is uninhabitable
- Common gap / deductible
- Review declaration and master policy
Personal Liability
Injuries or accidental damage to someone else’s property.
Protects you financially if someone is injured in your unit or if you accidentally damage another person's property. It can cover medical bills and legal fees.
Example: Accidental damage to another unit.
Personal auto exposures need auto insurance. Consider non-owned auto liability coverage if you drive a vehicle you do not own.
- What it covers
- Covers losses incurred by others resulting from your Unit
- Common gap / deductible
- Review declaration and master policy
Loss Assessment
Your share of a covered association loss.
Loss assessment coverage protects you if your association issues a special assessment to all owners to cover a loss that exceeds or is excluded by the association's master policy.
Example: A covered loss shared by owners.
Loss assessment coverage may exclude earthquake or volcanic earth movement; check your policy.
Critical: Loss assessment coverage is not a substitute for Dwelling coverage.
- What it covers
- Covers amounts specially assessed to individual Units based on a loss covered by a property's master insurance policy.
- Common gap / deductible
- Search loss assessment coverage to understand more. This coverage DOES NOT pay for dwelling and other aforementioned coverage types.
Loss Assessment: Two Examples
- 1Example One ONE: The common roof is in disrepair. The cost to repair it is beyond the available reserve funds. The association issues a special assessment to pay for the repairs. There is no insurance for "we failed to contribute adequately to our reserve fund" except selling your property before the assessment.
- 2Example Two TWO: The common roof gets blown off (this is called a loss). Your association's insurance pays for part, but not all of the roof repair and replacement. The association issues a special assessment. Your HO-6 policy loss assessment coverage pays up to your loss assessment limit.
Common HO-6 Insurance Endorsements and Riders
Homeowners almost always need to purchase riders for the following:
- Drain, Sewer, & Water Backup - Damage from backed-up water is almost always excluded and requires a specific rider.
Example: A drain backs up into your unit.
- Mold & Fungus (Bacterial Growth) - Standard policies often exclude or limit coverage for mold, especially if it results from long-term leaks or poor maintenance. An endorsement can cover remediation and repair costs.
Example: Mold repairs after a leak.
- Earth Movement & Earthquake - This is a standard exclusion and must be added separately, often at a significant cost.
Example: Earthquake damage to your home.
Deductible: If major earth movement and/or earthquake damage occurs, units/homes are typically assessed a portion of the association's primary EM and/or EQ deductible which is often a percentage of the building value (e.g. 2%, etc.)
- Valuables, Fine Art, & Electronics - Standard policies have low coverage limits for items like jewelry, art, and portable electronics. A rider can provide full replacement value.
Example: A valuable piece of jewelry.
- Equipment Breakdown - Protects appliances and personal electronics (cameras, computers, phones, TVs, etc.) from accidental damage and loss.
Example: Accidental damage to a computer.
- Personal Injury (Libel & Slander) - Protects against lawsuits for defamation (written or spoken), which are not covered by standard liability. In the age of social media, parents can be held liable for their children's online actions.
Example: A defamation claim over an online post.
Washington Documents
Coverage explanations, declaration language and volunteer references.
RCW 51.12.035: Volunteers
(1) Volunteers shall be deemed employees and/or workers, as the case may be, for all purposes relating to medical aid benefits under chapter 51.36 RCW.
A "volunteer" shall mean a person who performs any assigned or authorized duties for the state or any agency thereof, except emergency services workers as described by chapter 38.52 RCW, brought about by one's own free choice, receives no wages, and is registered and accepted as a volunteer by the state or any agency thereof, prior to the occurrence of the injury or the contraction of an occupational disease, for the purpose of engaging in authorized volunteer service: PROVIDED, That such person shall be deemed to be a volunteer although he or she may be granted maintenance and reimbursement for actual expenses necessarily incurred in performing his or her assigned or authorized duties.
Any and all premiums or assessments due under this title on account of such volunteer service shall be the obligation of and be paid by the state or any agency thereof which has registered and accepted the services of volunteers.
(2) Except as provided in RCW 51.12.050, volunteers may be deemed employees and/or workers, as the case may be, for all purposes relating to medical aid benefits under chapter 51.36 RCW at the option of any city, county, town, special district, municipal corporation, or political subdivision of any type, or any private nonprofit charitable organization, when any such unit of local government or any such nonprofit organization has given notice of covering all of its volunteers to the director prior to the occurrence of the injury or contraction of an occupational disease.
A "volunteer" shall mean a person who performs any assigned or authorized duties for any such unit of local government, or any such organization, except emergency services workers as described by chapter 38.52 RCW, or fire fighters covered by chapter 41.24 RCW, brought about by one's own free choice, receives no wages, and is registered and accepted as a volunteer by any such unit of local government, or any such organization which has given such notice, for the purpose of engaging in authorized volunteer services: PROVIDED, That such person shall be deemed to be a volunteer although he or she may be granted maintenance and reimbursement for actual expenses necessarily incurred in performing his or her assigned or authorized duties: PROVIDED FURTHER, That juveniles performing community restitution under chapter 13.40 RCW may not be granted coverage as volunteers under this section.
Any and all premiums or assessments due under this title on account of such volunteer service for any such unit of local government, or any such organization shall be the obligation of and be paid by such organization which has registered and accepted the services of volunteers and exercised its option to secure the medical aid benefits under chapter 51.36 RCW for such volunteers.
WAC 296-17-930 - Volunteers
Any city, town, county, school district, municipal corporation or any other political subdivision, or private nonprofit charitable organization electing to insure qualified volunteers under the authority of RCW 51.12.035 as now or hereafter amended, shall give the department written notice of its intent to provide coverage on a form prescribed by the department. Any employer insuring qualifying volunteers shall choose a reporting method option to apply to all qualifying volunteers. Employers have the option of choosing either:
- Maintaining records of all actual hours of work performed by each qualifying volunteer; or
- Reporting one hundred hours for each qualifying volunteer per calendar year (one hundred-hour cap method) rather than keep a record of actual hours for each qualifying volunteer per calendar year (see WAC 296-17-935).
Note: Election of reporting method is for each calendar year. Electing employers must report all of their qualified volunteers in the same manner each calendar year.
Note: Employers insuring qualifying volunteers must provide their reporting method (by selecting between either: Actual hours per qualifying volunteer or one hundred hours per such volunteer per calendar year) in the first quarter of the calendar year in which coverage for the volunteers is effective, along with the employer's regular quarterly report of payroll as prescribed by the department; see relevant reporting rules, including WAC 296-17-935.
The employer's office records shall include, in addition to records required under WAC 296-17-35201, written:
- Registration of each person who has volunteered; and
- Acceptance by the employer to perform work as a volunteer.
[Statutory Authority: RCW 51.04.020 and 51.16.035. WSR 16-18-085, § 296-17-930, filed 9/6/16, effective 10/7/16; Order 77-27, § 296-17-930, filed 11/30/77, effective 1/1/78; Order 75-28, § 296-17-930, filed 8/29/75, effective 10/1/75.]
Example Declaration Language
Insurance + Damage & Loss
13.7.1 Owner’s Additional Insurance
Each Unit Owner shall obtain and maintain an individual insurance policy which provides coverage for the Owner’s Unit (in an amount at least equal to the Association’s deductible) and personal belongings therein, and, to the extent reasonably available:
- A) Loss of use, loss of rental income, and loss Assessment exposures;
- B) Comprehensive Personal Liability coverage for any damage to other Units or Common or Limited Common Elements arising or resulting from the Owner’s negligence, carelessness, or acts or omissions, or from damage caused by fixtures or appliances maintained by the Owner; and
- C) The minimum Real Property coverage for an Owner policy shall not be less than the amount of the deductible for the Association’s policy of Property insurance, or any greater amounts as may be established by the Board.
- D) The minimum Loss Assessment coverage shall be the amount of the deductible for the Association’s policy of Property insurance.
- E) The Association may choose to purchase earthquake insurance for the Condominium. If it does, the Board may choose to require all owner’s to purchase earthquake insurance to cover the deductible under the Association’s policy that relates to their Unit.
- F) The Owner or Commercial Tenant of each Commercial Unit shall obtain and maintain property insurance covering all trade fixtures, equipment, appliances and improvements within the Commercial Unit made by any Commercial Owner or Commercial Tenant.
- G) The failure of an Owner to purchase insurance required under the Declaration does not reduce that Owner’s obligation to pay for amounts within the Association’s policy’s deductible, or any other amount for which the Owner is responsible under the Declaration.
13.7.2 Proof of Coverage
Unit Owners shall file a certificate of insurance for such individual policy or policies with the Board within thirty (30) days of any request by the Board. The Association shall have the right but not the obligation to monitor the maintenance of such insurance by Owners, and shall further have the right, but not the obligation, to obtain such insurance if the Owner or User fails to obtain or maintain the same and to levy a special assessment for the expense against the Unit(s) of the Owner(s) related to such Common Expense.
13.7.3 Unit Owner Obligations
The Association’s obligation to insure shall not relieve Unit Owners of their obligations under any other Article of the Declaration, including, but not limited to, the obligation to perform and pay for repairs, maintenance, care and replacement of the Unit and/or Limited Common Elements for which the Owner is responsible.
13.7.4 Tenant or Occupant Insurance
Unit Owners shall require any Tenants, Related Parties, or other Occupants to obtain Renter’s Insurance to protect their personal property, provide for loss of use, and to provide general liability insurance for acts and omissions by the Occupants and their guests, agents, pets and invitees.
13.7.5 Owner’s or Occupant’s Insurance Deductible
Under no circumstances shall the Association pay any insurance deductible due under a Unit Owner’s individual insurance policy or any Tenant’s or Occupant’s policy of insurance.
The Board may require a Unit Owner to file a claim under the Owner’s policy if the Owner is responsible for damage and has not otherwise paid their obligations for the necessary repairs.
11.15 Damages to Property
If, due to the act or neglect of a Unit Owner, Residential User or Commercial User, damage shall be caused to the Common Elements and facilities or to a Unit or Units owned by others, or maintenance, repairs or replacements shall be required which would otherwise be a common expense, then such responsible Unit Owner shall pay for such damage and such maintenance, repairs and replacements as may be determined by the Association, to the extent not covered by the Association’s insurance.
13.7.6 Allocation of Repair Costs for Property Damage
In accordance with the provisions of this Declaration, including but not limited to the subparagraphs of this section, the costs for repair or damage events are apportioned as follows:
13.7.6.1 Damage Covered by Association Insurance
For damage events that are covered by the Association’s insurance, repair costs over the Association’s standard insurance deductible are paid for by Association insurance, or by the Association if the Board decides not to file a claim. Repair costs within the Association’s standard insurance deductible are the responsibility of the Unit Owner and are allocated:
- (a) to the Owner if the damage resulted from neglect or misconduct of the Owner, the Owner’s Tenants or Occupants, or any of the Owner’s, Tenant’s, or Occupant’s guests, invitees, visitors, agents, or pets;
- (b) if there is no neglect or misconduct, then to an Owner, if the damage resulted from any vehicle, equipment, appliance or fixture (or wiring or pipes related thereto) within the Owner’s Unit or belonging to the Owner, the Owner’s Occupants or Tenants, or any of the Owner’s, Tenant’s, or Occupant’s guests, invitees, visitors, or agents;
- (c) if neither (a) nor (b) apply, then to an Owner whose Units or Limited Common Elements were damaged or benefited by the repairs;
- (d) if the damage is to more than one Unit and/or the Common or Limited Common Elements, and neither (a) nor (b) apply, the deductible is prorated between the Unit(s) and/or Common or Limited Common Elements based on the total benefit to each, as follows: (i) repairs to Units and Limited Common Elements that benefit only one Unit will be assessed solely to the individual Unit Owners; (ii) repairs to Limited Common Elements that benefit more than one Unit will be assessed to the Unit Owners benefitted; and (iii) repairs to Common Elements will be assessed as Common Expenses, divided among Owners in accordance with the formula specified for other Common Expenses.
13.7.6.2 Damage Not Covered by Association Insurance
For damage events that are not covered by the Association’s insurance, repair costs shall be assessed:
- (a) to the Owner if the damage resulted from neglect or misconduct of the Owner, a Related Party, the Owner’s Tenants or Occupants, or any of the Owner’s, Tenant’s, or Occupant’s guests, invitees, visitors, agents, or pets;
- (b) if there is no neglect or misconduct, then to an Owner, if the damage resulted from any vehicle, equipment, appliance or fixture (or wiring or pipes related thereto) within the Owner’s Unit or belonging to the Owner, the Owner’s Occupants or Tenants, or any of the Owner’s, Tenant’s, or Occupant’s guests, invitees, visitors, or agents;
- (c) if neither (a) nor (b) apply, then to an Owner whose Units or Limited Common Elements were damaged or benefited by the repairs; or
- (d) to the extent that the damage to the Property is not insured, and not the responsibility of an individual as noted above, then the Association shall restore all Common Elements and Limited Common Elements as a common expense, and Owners shall restore their Units at their own expense.
13.7.7 Maximum Damage Assessment
Except to the extent covered by an Owner’s or Tenant’s insurance policy, the maximum one Unit can be assessed for any one damage event is the deductible under the Association’s standard Property policy. Amounts within deductibles for earthquake or flood damage in excess of the standard Property deductible, combined with contributions required of Owners as provided for in this Declaration, shall be a common expense. This maximum shall not apply to Owners who cause damage through negligence or misconduct, or for their responsibility for equipment failure.
20.1 Liability for Utility Failure, Leaks, Etc
Except to the extent covered by insurance obtained by the Association, or negligence on the part of the Association, neither the Association nor the Board shall be liable for: any failure of any utility or other service to be obtained and paid for by the Association; or for injury or damage to persons or property caused by the elements, or resulting from electricity, noise, smoke, water, rain (or other liquid), dust or sand which may leak or flow from outside or from any parts of the buildings, or from any of its pipes, drains, conduits, appliances, or equipment, or from any other place; for damage or injury alleged as a result of mold or other microorganisms; or for inconvenience or discomfort resulting from any action taken to comply with any law, ordinance or orders of a governmental authority. No diminution or abatement of Common Expense Assessments shall be claimed or allowed for any such utility failure or water leak, or for such injury or damage, or for such inconvenience or discomfort.
Except to the extent covered by insurance obtained by the Association, or negligence on the part of the Association, the Association is not responsible for loss of use of a Unit, nor for loss of rental income for a Unit. The Association is not responsible to provide for the safety or security of persons or property at the Condominium. The Association is not responsible to move or store personal property of owners or occupants because of any casualty event, or as needed to accommodate repairs to common elements.
20.2 Liability for personal property and relocation
Owners are responsible to relocate and store their personal property if required to allow for the repair, restoration or replacement of any common element or any other work for which the Association is responsible. Except to the extent covered by insurance obtained by the Association, or negligence on the part of the Association, if a Unit must be vacated to allow for repair, restoration or replacement, the Owner is responsible for alternative housing accommodations for any occupants of the Unit. There shall be no contribution by the Association for any costs or inconvenience to occupants incurred as a result of the Association carrying out its obligations to maintain and repair the property.
4.3 Items Included in the Units
Each Unit includes:
4.3.1 The paneling, tiles, wallpaper, paint, finished flooring, and any other materials constituting any part of the finished surfaces thereof.
4.3.2 The outlets of any utility service lines such as water, sewage, gas or electricity and ventilating ducts within the Unit;
4.3.3 Electrical panels, lights, fans, outlets, switches and any other electrical fixture in or connected to the Unit are part of the Unit. (Wires inside the walls and floors serving only one Unit are Limited Common Elements assigned to the Unit.)
4.3.4 Valves, drains, traps, supply lines, wax rings, and other plumbing fixtures in or connected to the Unit are part of the Unit. (Pipes inside the walls and floors serving only one Unit are Limited Common Elements assigned to the Unit.)
11.11.2 Fixtures
Each Unit Owner shall be responsible for the maintenance, repair or replacement of plumbing lines, hoses and fixtures, water heaters, fans, heating, cooling, or other equipment, fireplace flues (including required inspections and cleaning) and electrical fixtures or appliances which may be in, or are part of, or serve only the Unit (including HVAC condensers located outside the boundaries of a Unit).
Owners are responsible for the maintenance and repair of water pipes, drains, and wires which are within or serve only their Unit. Included in the Owner’s responsibility are: shower valves; shutoff valves; toilet wax rings; supply lines and drains under sinks; and shower and tub drains and overflows, including the traps. See Exhibit E for more detail Owner responsibility for maintenance, repair and replacement of building components. If a clogged pipe only affects one Unit, it is assumed to serve only that Unit, and the cost to clear the pipe is either a Limited Common Expense for the unit, or an expense that only benefits that Unit. Water supply pipes downstream from the shutoff valve serving the Unit are Limited Common Elements and the responsibility of the Owner as further described in Exhibit E.
10.2.8 Entry for Repairs
Upon prior Notice, except in case of an emergency, each Unit Owner must afford to the Association, and to its agents or employees, access into and through that Owner's Unit and Limited Common Elements reasonably necessary for maintenance and repair of the property, including necessary inspections by the Association. The Board and its agents may enter any Unit or Limited Common Elements appurtenant thereto when the Board deems necessary in connection with any inspection, maintenance, repair, landscaping or construction carried out by the Board, in the event of an emergency, or in connection with any maintenance or other necessary repairs, replacement, construction, or other activity for which the Unit Owner is responsible but has failed to perform.
In furtherance of the foregoing, the Association shall have the right at all times to possess such keys, lock combinations, alarm codes and/or instruments of access as are necessary to gain immediate access to all Units. Owners must provide keys or other means of access within ten (10) business days of a request by the Association or its Managing Agent.
Such entry shall be made with as little inconvenience to the Owner and/or Occupant as practicable. Except in emergencies, Notice shall be provided at least five (5) business days in advance, and shall be posted on the door to the Unit at least forty-eight (48) hours in advance of entry.
The Association shall maintain complete records of all inspections, maintenance, repairs and replacements done by it or its agents or contractors with respect to the Common Elements, Limited Common Elements or Units. Any damage caused to a Unit or Limited Common Element due to the aforementioned activities shall be repaired by the Association as a Common Expense.
Each Owner shall provide the Association access into their Unit for compliance with this Section. Common expenses incurred due to an Owner’s failure to provide access will be assessed to the Unit.
- a) If damage is inflicted on the Common Elements or on any Unit through which access is taken, the Unit Owner responsible for the damage, or the Association if it is responsible, is liable for the prompt repair of the damage.
- b) If an Owner or other occupant is displaced due to fire, damage, or necessary repairs to the condominium, the Association has no liability for the cost of moving, storage, or alternative housing. These are risks that each owner can insure themselves for. If an Owner refuses to remove the occupants or contents of a Unit when necessary for the Association to perform its work, any costs incurred by the Association for the removal or protection of persons or contents shall be assessed against the Owner and the Unit.
Interim Policy 61.06 - Workers' Compensation Insurance Coverage for Volunteers
WAC 296-17A-6901 - Classification 6901
WAC 296-17A-6901 - Classification 6901
6901-00 Volunteers
Applies to the medical aid coverage for volunteers of state agencies, municipal corporations, political subdivisions, or private nonprofit charitable organizations. Medical aid coverage is mandatory for volunteers of state agencies. Medical aid coverage is optional for volunteers of city, county, town, special district, municipal corporations, political subdivisions, or nonprofit charitable organizations.
This classification excludes student volunteers of private sector employers who are to be reported separately in classification 6901-01; volunteer law enforcement officers of cities, towns, counties and taxing districts for whom medical aid only coverage has been elected who are to be reported separately in classification 6906; and volunteer law enforcement officers of cities, towns, counties, or Native American tribal councils for whom full coverage has been elected who are to be reported separately in classification 6905.
Special note: To elect coverage for volunteers, employers or charitable organizations must submit a completed Application for Optional Coverage to the department. Conditions of coverage are outlined on the application. State Fund workers' compensation is not provided to volunteer firemen covered by chapter 41.24 RCW and emergency services workers covered by chapter 38.52 RCW.
This policy explains what a volunteer is, and when volunteers are or may be covered for Workers' Compensation benefits. “Volunteer coverage” provides for medical aid benefits only.
Policy point 1
1. A volunteer is a person who donates labor to another by his or her own free choice without receiving material or monetary or other value in exchange.
The business or organization may provide volunteers with maintenance and reimbursement for actual expenses necessarily incurred. “Maintenance” includes things such as meals and transient sleeping quarters incurred while performing assigned or authorized volunteer duties. However, if a person receives any type of material or monetary or other value in excess of the expenses, he or she may be considered a covered worker.
If a business or organization claims someone as a volunteer and pays the person a “stipend,” the amount paid and its relation to the work performed must be evaluated to determine whether it is maintenance and reimbursement or is value or compensation for labor provided.
Gifts of appreciation do not transform a volunteer into a worker and must be evaluated to determine whether they are maintenance or reimbursement, a token of appreciation, or compensation for labor provided.
Unpaid job training received with the promise of a future paid job with a specific employer is considered value in exchange for work performed. The trainee is a covered worker. Exception: If the job training is performed by a student volunteer or unpaid student in a school-approved program, the training is not considered covered work and elective volunteer coverage may be available. See policy point #7.
True “volunteers” fall outside Title 51 with two exceptions:
Policy point 2
2. An employer may not elect either full coverage or “volunteer coverage” unless such elective coverage is provided for in Title 51.
Policy point 3
3. For-profit businesses are generally presumed not to have volunteers.
In some limited circumstances, the department may recognize an individual as a volunteer when the business can show:
- Both parties intended volunteer status in advance of the work, and
- No remuneration is offered beyond maintenance and reimbursement expenses as described above policy point #1) above, and
- The work is similarly advantageous to both the business and the worker volunteer such as in circumstances where goodwill is being provided by the worker in an emergency on a temporary basis,1 and
- The volunteer is not a member of a vulnerable or penal population. Examples of persons from a vulnerable or penal population include, but are not limited to:
- Members of a work release population;
- Persons in substance abuse treatment;
- Economically disadvantaged individuals who are long-term jobless or homeless.
Volunteer status at for-profit businesses can include situations such as:
- Adult family members related by blood within the third degree or marriage2 working at a family business in emergency situations on a temporary basis;
- Work that constitutes a hobby activity;
- Limited work that constitutes a grant of professional or personal goodwill, such as a close family friend who volunteers to assist in a small grocery store for a short time while the owner's spouse is sick.
NOTE: Each situation will be reviewed in full context of relevant facts to determine status.
1 Other employment and wage laws may or may not recognize volunteers at for-profit enterprises.
2 See analogous language in RCW 51.12.020. This language includes a person and that person?s spouse, children, grandchildren, great grandchildren, brothers and sisters, nephews and nieces, parents, grandparents, great grandparents, and aunts and uncles. Cousins are not related by blood within the third degree. Legal adoptions or step relatives are considered as if genetically related.
Policy point 4
4. Workers' compensation coverage is not available to volunteers of for-profit businesses except as described in policy point #7.
Policy point 5
5. State government agencies must provide their registered volunteers with “volunteer coverage,” which provides medical benefits only.
Exception: Workers' compensation coverage for volunteer emergency services workers is not available. The Department of Emergency Services administers these volunteer
activities, which can include, but are not limited to:
- mountain search and rescue,
- explorer scout trackers,
- clean-up after volcanic eruptions, and
- sandbagging during floods.
The local jurisdiction, usually the sheriff's office, registers these volunteers and typically issues an identification card to the emergency worker volunteer.
Policy point 6
6. Other government agencies for any city, county, town, special district (such as a public utility district or PUD), municipal corporation or any other political subdivision may elect to provide their registered volunteers with “volunteer coverage,” which provides medical benefits only:
Exceptions: 6a. Agencies cannot elect coverage for volunteer firefighters which includes fire fighters and emergency medical technicians who support firefighting activities. These volunteers are covered under the Volunteer Firemen’s Relief and Pension Fund.
6b. Agencies cannot elect coverage for registered emergency worker volunteers in policy point #5.
6c. Law enforcement agencies may elect either full coverage, reported in classification 6905, or “volunteer coverage”, reported in classification 6906, for their non-clerical law enforcement volunteers. These agencies must cover all their law enforcement volunteers with the same type of coverage.
Policy point 7
7. Certain employers may elect “volunteer coverage” for qualifying student volunteers or unpaid students.
The entity receiving the service is the employer, who may elect volunteer coverage, and is responsible for premiums (Classification 6901).
Distinction between student volunteers and unpaid students:
Student volunteers are:
- Currently enrolled in school or higher education, and
- Receiving no wages for the services, and
- Participating in a program approved or sponsored by their school.
Unpaid students are:
- Currently enrolled in an institution of higher education (beyond K-12), and
- Participating in a school-sponsored, unpaid work-based learning program, including, but not limited to, cooperative education, clinical experiences, or internship programs, and
- Receiving something of educational value from the school, such as credit or other educational value (such as completion of clinical hours) in return for the services they provide for the employer.
Example of an unpaid student, eligible for elective volunteer coverage:
Janet is a student enrolled in the veterinary assistant program at community college. To complete the course of study and receive her degree, the school requires her to complete 100 hours of clinical experience with a veterinarian. Dr. Brown is a veterinarian and has agreed to allow Janet to work in his veterinary business to earn the needed 100 hours of experience. Janet is not paid for her work for Dr. Brown. The work at Dr. Brown's veterinary clinic is approved by Janet's school. Janet qualifies as an unpaid student under this rule. Dr. Brown is her employer, and may elect medical aid only coverage for Janet.
Policy point 8
8. A private, non-profit charity may elect to provide its registered volunteers with “volunteer coverage.”
To be considered a private non-profit charity, an organization must demonstrate that it qualifies under Internal Revenue Service (IRS) rules as a 501(c)(3) exempt organization. Under IRS rules, churches automatically qualify. All other non-profit charities should have a letter from the IRS saying they qualify.
Policy point 9
9. Workers' compensation coverage is not available for volunteers of non-profit organizations that are not charitable organizations as defined by relevant IRS rules except as described in policy point #7. Examples of entities that may not meet the IRS definition of charitable organizations may include:
- Homeowner’s associations
- Chambers of Commerce
- Fraternal organizations and clubs, such as the Eagles, Elks, Lions, Mountaineers, and Veterans of Foreign Wars (VFW).
Policy point 10
10. An employer who qualifies under policy points 5, 6, or 7 may elect “volunteer coverage”.
If a qualified employer chooses to elect “volunteer coverage”, it must:
- Submit a completed “Application for Elective Coverage of Excluded Employments” form to the department. The effective date of coverage will begin at 12:01 a.m. on the day after the department receives the request unless a later date is requested.
- Notify its volunteers that the employer is electing coverage.
- Cover all its volunteers and report all their hours.
Policy point 11
11. All employers reporting volunteer coverage in classifications 6901 or 6906, may choose a reporting method of either 100 hours per volunteer per calendar year (100-hour cap method), or actual hours worked.
Starting June 9, 2016, employers with volunteer coverage may notify the department in writing that they choose to report 100 hours per volunteer per calendar year rather than reporting actual hours.
Starting January 1, 2017, employers will choose which reporting method they want when filing their first quarterly report of the year. They must report all volunteers using the same method for the calendar year. If an employer hires additional volunteer(s) in a subsequent quarter, the employer must report the additional volunteer(s) in the next quarter after hiring using the same election method (100 hours or actual hours) for all additional volunteers hired.
NOTE: Employers may choose to change their reporting method each calendar year. If no choice is made, the default reporting method is actual hours.
Policy point 12
12. Employers who have elected volunteer coverage for qualified volunteers may cancel the coverage by notifying the department in writing.
The employer must notify its volunteers that coverage is being cancelled.
The cancellation is effective 30 days after the department receives written notice of cancellation.
WAC 296-17-930 - Volunteers
Any city, county, school district, municipal corporation or any other political subdivision, or private nonprofit charitable organization electing to insure volunteers under the authority of RCW 51.12.035 as now or hereafter amended shall give notice in writing on a form prescribed by the department. Any employer having elected to insure volunteers shall maintain office records of all hours of work performed by volunteers. Such office records shall include notice in writing as a registration of each person who has volunteered and has been accepted by the employer to perform work as a volunteer. A report of such hours will be included with the employer's regular quarterly report of payroll as prescribed by the department, and will include payment for the premium based on such hours and at such rates per hour as assigned by the department.
https://lni.wa.gov/forms-publications/F213-023-000.pdf ~ info from link pasted below
Who is a volunteer?
A volunteer is a person who donates labor to another by his or her own free choice. Generally, the volunteer doesn’t receive anything of value in exchange for the service — not money, trade of products or services, or anything else of monetary value.
When is a volunteer a “covered worker”?
If a volunteer receives something of monetary value in exchange for work, he or she is probably a “covered worker” who is entitled by law to workers’ compensation insurance coverage.
Maintenance and reimbursed expenses
Your business or organization may provide volunteers with maintenance and reimbursement for necessary actual expenses. “Maintenance” includes things such as meals and transient sleeping quarters while performing assigned or authorized volunteer duties. However, if a person receives any type of money or other value in excess of the expenses, he or she may be considered a covered worker.
Stipends
If your business or organization claims someone as a volunteer and pays the person a stipend, the amount paid and its relation to the work performed must be evaluated to determine whether it is maintenance and reimbursement or is compensation for labor provided.
Gifts of appreciation
Gifts of appreciation do not transform a volunteer into a worker, and must be evaluated to determine whether they are maintenance or reimbursement, a token of appreciation, or compensation for labor provided.
Unpaid job training
Unpaid job training received with the promise of a future paid job with a specific employer not in connection with a school-approved program is considered value in exchange for work performed.
Questions?
If you have questions about volunteer status, contact our Workers' Comp Coverage Determinations Unit at Determinations@Lni.wa.gov or 509-324-2627 for a determination of coverage.
Note: Each situation will be reviewed in full context of the relevant facts to determine status. If workers do not meet the criteria above, they are presumed to be employees. In addition to workers' compensation insurance coverage requirements, other employer requirements such as minimum wage, unemployment insurance, social security, and Medicare may apply.
Volunteers (Washington L&I) ~ info from link pasted below
Who can elect to cover volunteers?
In Washington, some organizations may choose to purchase volunteer coverage, or workers’ compensation coverage for medical costs only. Volunteer coverage does not include the other usual benefits of workers’ compensation, such as wage replacement, vocational and retraining costs, permanent partial disability payments, or death benefits.
Organizations that may elect to buy volunteer coverage (medical only) include:
- Cities, counties, towns, special districts (such as public utility districts), municipal corporations, or other political subdivisions
- Employers with student volunteers enrolled in public and private K–12 schools and schools of higher education. For more details, see Student volunteers, unpaid students and workers' compensation coverage or our Student Volunteers and Workers' Compensation Coverage fact sheet (F213-023-000).
- Private non-profit charities that are able to demonstrate they qualify under Internal Revenue Service (IRS) rules as a 501(c)(3) exempt organization.
Exceptions:
- State government agencies must provide their registered volunteers with volunteer coverage.
- Volunteer firefighters are covered under the Volunteer Fireman’s Relief and Pension Fund.
- Law enforcement agencies may choose full coverage or medical-only volunteer coverage. All volunteers must be covered with the same type of coverage.
How to start coverage
To elect volunteer coverage, you must submit an Application for Elective Coverage of Excluded Employment form (F213-112-000). Coverage starts at 12:01 a.m. the day after we receive your completed form, or you may choose a future effective date.
If your business or organization elects to cover volunteers, you must:
- Cover all your volunteers and notify them of coverage.
- Choose whether to report all volunteers based on actual hours or based on 100 hours per volunteer per calendar year.
- Report and pay premiums for either all volunteer hours worked, or for 100 hours per volunteer per calendar year.
- Create auditable records of all volunteers and keep these records for 3 full calendar years. Records must include:
- Names and Social Security numbers.
- Registration and acceptance of each person as a volunteer for your organization.
- Beginning and end date of volunteer service.
- Applicable risk classifications (likely 6901 or 6906).
- Actual hours worked, or your decision to report 100 hours per volunteer per calendar year.
- For student volunteers and unpaid students:
- Proof of registration showing the student's current enrollment in school or an institution of higher education.
- Authorization from the school or institution of higher education for the student's participation in the school's volunteer or unpaid work-based learning program.
How to cancel coverage
If your business or organization chooses to cancel volunteer coverage, you must notify all volunteers that you are cancelling coverage. The cancellation is effective 30 days after we receive your written notice of cancellation.
To cancel volunteer coverage, you may use the Cancellation of Elective Coverage for Excluded Employments form (F213-005-000) or another written form of notification.
State government agencies
State government agencies must provide their registered volunteers with “volunteer coverage.”
Exception: Workers’ compensation coverage for volunteer emergency services workers is not available. The Department of Emergency Services administers these volunteer activities, which include but are not limited to:
- Mountain search and rescue
- Explorer scout trackers
- Clean up after volcanic eruptions
- Sandbagging during floods
The local jurisdiction, usually the sheriff’s office, registers these volunteers and typically issues an identification card to the emergency worker volunteer.
Workers’ Compensation: Jobs and Risk Classes
What type of job is the employee going to perform? [These are examples from Washington State]
If they are performing jobs that are maintaining or repairing the existing property, such as replacing windows, plumbing, flooring, or repainting, you would report them in 4905 (Motels and Hotels) or 4910 (Property and Building Management Services). See below. Washington State Risk Class Lookup
If they are performing jobs adding new construction or altering the interior of an existing building from an earlier condition (remodeling), or enlarging an existing structure by building and attaching rooms (new addition), you would report them in the applicable construction classification. See examples below.
Examples
- Windows: Replacing one or all windows in a building for weatherization purposes is considered general maintenance and repair, reportable in 4905 or 4910.
- Painting: Repainting the interior or exterior of a building, whether it’s part or all of the building, is considered general maintenance and repair and is reportable in 4905 or 4910.
- Flooring covering: Replacing flooring in a building, whether you are replacing the old flooring with the same type or a different type (changing from vinyl to hardwood), is considered general maintenance and repair, reportable in 4905 or 4910.
- Roofing: Re-roofing a building, whether you’re replacing a small section of the roof or the entire roof, and regardless of whether you’re replacing with the same type of material, is considered general maintenance and repair, reportable in 4905 or 4910.
- Maintenance and repair: Bringing something back to its original state or functionality. An apartment complex has a set of stairs in need of repairs. Tearing out the old stairs and replacing them with new stairs would be considered maintenance and repair. This would be reportable in risk classification 4910.
- Improvements: An apartment complex decides to install a sprinkler system (inside or outside) on the premises. The installation of the sprinkler system would be considered an improvement to the property, and this work would be reportable in the applicable construction classifications. Repairing an existing sprinkler system is considered maintenance and reportable in 4910.
- New Construction: An apartment complex owner wants to build an outbuilding on the property for their landscaping tools. They are building something that does not currently exist. This work would be reportable in the applicable construction classifications.
- Alteration: A property management company wants to add some interior walls in an apartment of one of their complexes. The walls did not exist previously and they are changing something that currently exists into something different. This work would be reportable in the applicable construction classifications.
Special Note
Construction contractors who own and manage their own rental properties must report all construction, maintenance and repair activities in the applicable construction classification for workers preparing properties for initial occupancy or to sell. When properties are ready for occupancy, any future maintenance and ordinary repairs performed by the construction contractor’s workers may be reported in 4910, if applicable.
- Preoccupancy clean-up may be reported in 6602.
- Employees who only perform clerical duties are to be reported separately in classification 4904.
- Employees who perform sales duties such as collecting rents, showing and advertising the facility, conducting auctions, or a combination of clerical and sales duties are to be reported separately in classification 6303.
Articles and Reference
Key Terms
Business insurance is a general term that includes a gamut of different coverages.
Workers' Compensation
Workers' Compensation insurance often excludes volunteers. Five states (North Dakota, Ohio, Washington, West Virginia, and Wyoming) run their own programs for workers' comp coverage. Washington State Department of Labor & Industries (L&I) does not offer coverage for volunteers.
Many CICs do not realize that they possess little to no insurance coverage for bodily injuries incurred by their volunteers.
Washington State Administrative Code (WAC) clarifies statutes related to workers' compensation and risk classifications.
Condominium and HOA employees are generally included with either Classification 4904 (clerical) OR the much broader (more expensive) Classification 4910 (property management services).
- 2023 base rate and payroll deduction for Classification 4904
- 2023 base rate and payroll deduction for Classification 4910
WA State L&I also tracks hourly wage rates for specific risk classifications that may receive alternative forms of non cash-compensation.2022's average wage for class 4910 = $33.50/hour.
Notably, according to WAC 296-17-31018(4), many classifications (incl. 4910) exclude coverage for alterations and new construction.
Alterations are changes made to a building during its remodeling, such as increasing or reducing floor area, making or closing openings, erecting or demolishing walls, etc.
Insurance Articles
Insurance Articles
- Need some practical advice to understand a project?
- Reinvigorate your governing documents
- Gauge owner satisfaction and increase engagement
- Does service from your management company meet expectations?